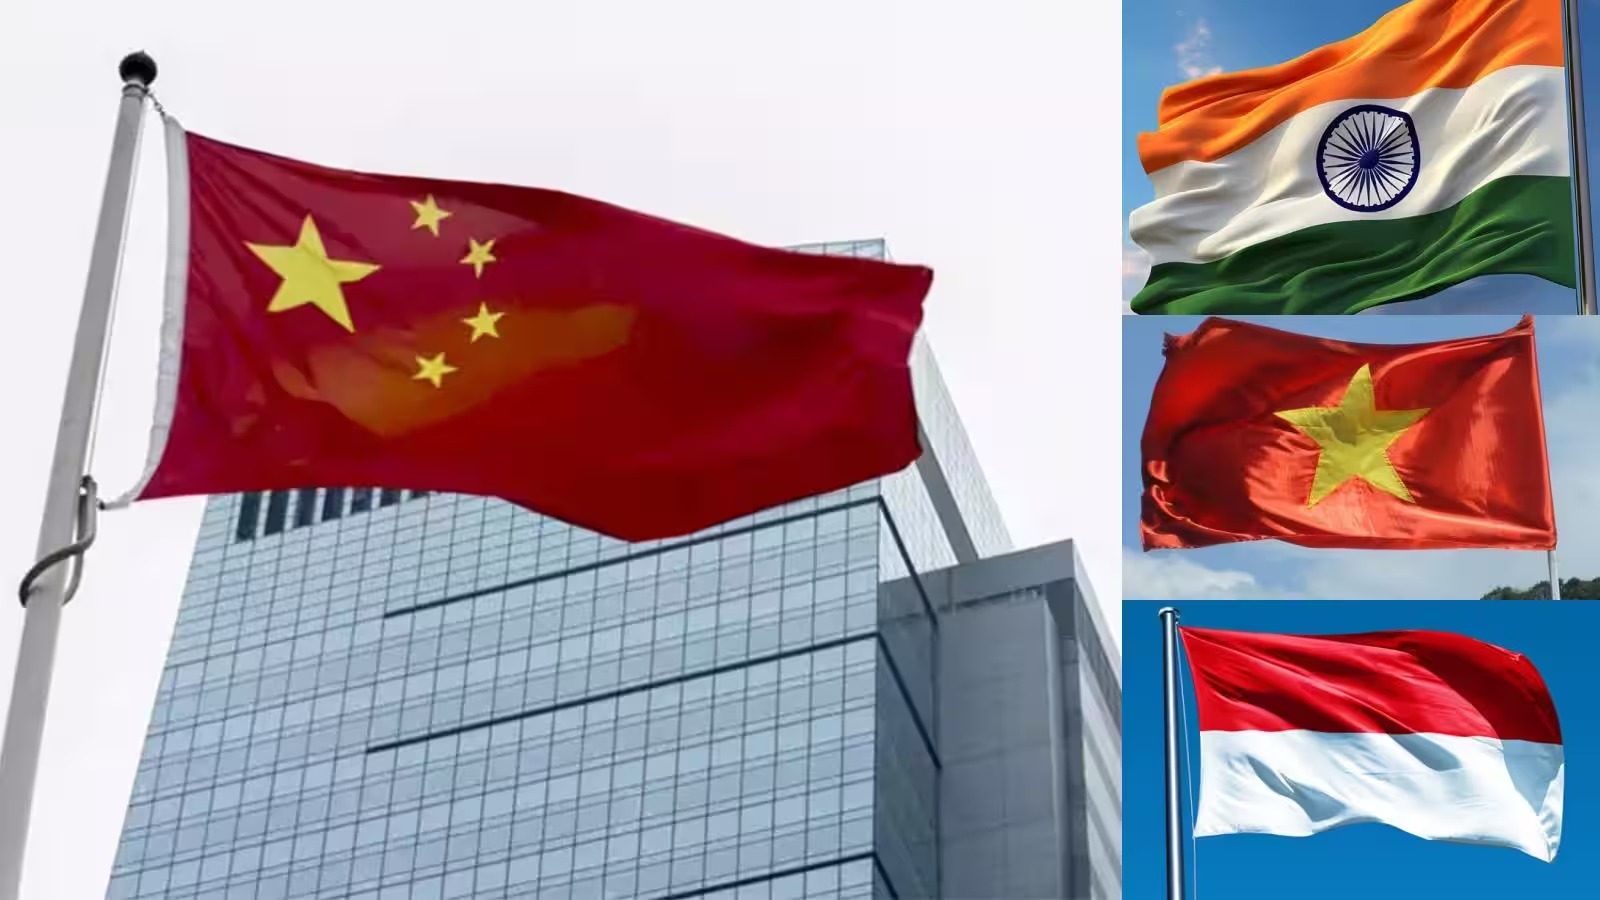
Global firms are rethinking their China-plus-one supply chain strategies as smaller manufacturing hubs encounter scaling bottlenecks, rising costs, and upstream component dependencies. Enterprises are shifting toward robust, multi-market industrial ecosystems that offer deeper supplier networks and long-term operational resilience.
Global Firms Rethink China-Plus-One Supply Chain Strategies
Global manufacturers are recalibrating their diversification playbooks, moving beyond initial Southeast Asian hubs to evaluate deep-market alternatives.
As supply chain pressures, shifting trade tariffs, and complex regulatory frameworks reshape international manufacturing, multinational corporations are actively rethinking the standard China-plus-one strategy. While nations like Vietnam initially captured the bulk of early relocation capital for assembly and electronics processing, corporations are increasingly discovering structural limits regarding scale, domestic consumption depth, and upstream component ecosystems. Consequently, boardrooms across North America, Europe, and East Asia are adopting a more nuanced approach—balancing compact export economies with large-scale manufacturing powerhouses like India.
Limits of Early Sourcing Hubs and Scale Pressures
In the initial phases of supply chain re-engineering, smaller Southeast Asian economies served as primary destinations due to established export infrastructure and lower entry costs. However, recent industrial assessments highlight growing operational bottlenecks.
According to trade logistics data and manufacturing analyses, rapid capacity expansion in localized corridors has driven up land and labor costs while straining secondary supplier networks. Many facilities operating outside China continue to rely heavily on imported raw inputs and intermediate sub-components originating from Chinese industrial centers. When global demand scales up rapidly, these regional limitations often result in longer lead times and higher defect remediation rates, forcing logistics executives to seek more self-sustaining ecosystems.
The Shift Toward Multi-Pronged Industrial Ecosystems
To address these vulnerabilities, multinational enterprises are transitioning from a simple binary relocation model to an integrated multi-hub framework. Industry observers note that while nations like Vietnam remain efficient for specific labor-intensive assembly lines, complex sectors—such as heavy automotive engineering, advanced electronics, chemicals, and pharmaceuticals—demand broader industrial depth, skilled engineering talent, and massive domestic consumer markets.
Governments and trade organizations are responding with targeted policy measures. India's large-scale manufacturing incentives, coupled with massive logistics investments under dedicated freight corridors, have positioned the nation as a primary anchor for firms seeking long-term operational resilience rather than temporary cost arbitrage.
Official Sources Section
Insights regarding global trade shifts and manufacturing trends are sourced from industrial economic bulletins, multilateral trade reviews published by UNCTAD, global supply chain advisory reports from the World Trade Organization (WTO), and cross-border investment analyses.
"The pursuit of supply chain resilience has evolved past simple geographic hedging; companies are now demanding deep local supplier ecosystems, technical scalability, and robust domestic market integration," trade analysts stated.
Practical Implications for Global Investors and Consumers
For corporate planners and international investors, the evolution of the China-plus-one model means that site selection must account for multi-tier supplier availability rather than final-assembly convenience alone. For consumers, diversified manufacturing footprints help cushion retail markets against localized shocks, pandemics, or regional trade disputes, stabilizing long-term pricing for consumer goods and technology hardware.
Key Facts at a Glance
Strategy Evolution: The initial "China-plus-one" approach is expanding into multi-geography sourcing models to eliminate single-point vulnerabilities.
Bottlenecks Identified: Smaller manufacturing hubs face rising land costs, labor constraints, and heavy reliance on imported intermediate components.
Core Advantage: Markets offering deep domestic consumption, robust engineering talent pools, and automated industrial corridors are gaining preference for complex production lines.
Target Sectors: High-tech electronics, pharmaceuticals, specialty chemicals, and heavy automotive components are leading the next wave of diversification.
Frequently Asked Questions
What is the China-plus-one manufacturing strategy?
It is a risk-mitigation approach where multinational companies maintain core operations in China while establishing parallel manufacturing or sourcing footprints in at least one other country.
Why are firms rethinking their reliance on smaller Southeast Asian hubs?
While effective for initial assembly, smaller hubs frequently face scalability limits, rising labor costs, and a heavy dependence on imported upstream components.
How do large-scale alternative markets differ in manufacturing capability?
Larger industrial economies offer broader domestic consumer bases, extensive sub-tier supplier networks, and deep engineering talent pools suited for complex, high-volume production.
What role do government policies play in current supply chain shifts?
Targeted production incentives, infrastructure investments, and streamlined trade corridors heavily influence where multinational firms establish their long-term manufacturing bases.
Source: UNCTAD World Investment Reports, World Trade Organization (WTO), International Trade Administration