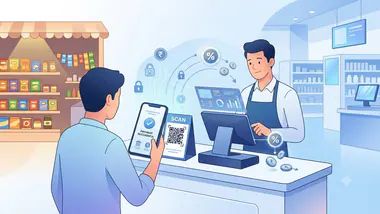
Unified Payments Interface transactions are seeing structural adjustments as new regulatory guidelines and merchant conditions apply. While peer-to-peer transfers remain accessible, specific commercial transactions and prepaid instrument structures introduce conditional fees, marking a nuanced evolution in India's digital public infrastructure payment models.
Navigating shifts in digital financial frameworks, regulatory updates and merchant guidelines introduce new conditions that alter the free structure of UPI transactions.
As digital financial ecosystems continue to mature across South Asia, recent regulatory and banking adjustments have brought significant changes to how transactions are processed. In September 2026, financial authorities and payment aggregators confirmed that while standard peer-to-peer (P2P) transfers remain accessible, specific commercial tiers, prepaid wallet linkages, and high-volume merchant settlements under the Unified Payments Interface (UPI) are subject to new conditions and structured fees. The policy adjustments aim to ensure the long-term sustainability of payment infrastructure while addressing the operational costs borne by banks and fintech service providers.
Evaluating Payment Infrastructure, Merchant Fees, and Regulatory Guidelines
Analyzing the structural modifications within the payment network reveals a calculated effort to balance financial inclusion with infrastructural sustainability. According to official regulatory updates and banking circulars released in September 2026, key aspects of the transition include:
Distinguishing Peer-to-Peer and Merchant Payments: Everyday transfers between individual bank accounts remain free of direct user charges, preserving everyday accessibility.
Prepaid Payment Instruments (PPI) and Wallets: Transactions executed via third-party wallets linked to UPI identifiers may attract interchange fees under specific merchant categories.
Sustaining Digital Infrastructure: Financial authorities emphasize that processing billions of monthly transactions requires continuous investments in server capacity, cybersecurity, and fraud prevention systems.
Banking and FinTech Compliance: Payment service providers are mandated to ensure transparent disclosure of any applicable merchant discount rates (MDR) or transaction fees prior to payment completion.
Why It Matters
The practical implications of conditional fee structures on UPI impact millions of daily retail consumers, small business merchants, and fintech operators across India. For everyday users, standard peer-to-peer money transfers remain completely unaffected and free. For merchants and commercial vendors, understanding applicable transaction fees and merchant discount rates is essential for accurate business accounting and digital checkout management.
Key Facts at a Glance
Core Change: UPI transactions are no longer universally free under all circumstances, with specific conditions applying to commercial and wallet-based transfers.
P2P Protection: Standard person-to-person bank transfers continue to remain free of direct consumer charges.
Governing Bodies: Managed under guidelines issued by the Reserve Bank of India (RBI) and NPCI.
Primary Objective: Ensuring the long-term technological and financial sustainability of India's digital payment infrastructure.
FAQ Section
Are all UPI transactions now subject to fees?
No. Standard peer-to-peer (P2P) transfers between individual bank accounts remain completely free for users.
Which transactions are affected by the new conditions?
Conditional fees or interchange rates primarily apply to specific commercial merchant transactions, prepaid wallet (PPI) linkages, and high-volume business accounts.
Why are these conditions being introduced to UPI?
Financial authorities and network operators are implementing structural adjustments to support the massive operational, security, and maintenance costs of processing billions of monthly transactions.
How can users check if a transaction incurs any charges?
Payment apps are mandated to display any applicable merchant fees or charges transparently before the user authorizes the final payment.
Where can readers find official circulars regarding UPI guidelines?
Complete policy documents and regulatory updates are accessible via the Reserve Bank of India (RBI) Portal and the National Payments Corporation of India (NPCI).
Source: Reserve Bank of India (RBI), National Payments Corporation of India (NPCI), The Economic Times, Mint