Indian citizens permanently relocating overseas must immediately restructure their domestic financial portfolios to comply with strict sovereign foreign exchange regulations. Expatriates must liquidate secondary pension accounts and convert fixed deposits into non-resident structures. Proper compliance minimizes domestic tax liabilities while ensuring individuals meet mandated reporting requirements across foreign tax jurisdictions.
New
expatriates face specific rules on pension accounts, fixed deposits and
cross-border tax reporting once they change residency status.
NEW DELHI -
Packing up your life to move abroad comes with a checklist most people don't
think about until it's too late: what happens to your PPF and NPS accounts back
home. Under India's Foreign Exchange Management Act, non-resident status
triggers a set of mandatory changes to how these retirement and savings
instruments are held and getting it wrong can mean frozen accounts, tax
penalties, or both.
Don't
Panic-Close Everything
Here's the
first mistake financial advisors say they see constantly: people assume they
need to shut down every Indian account before boarding their flight. That's not
actually true, and doing it can create more tax headaches than it solves.
What is true
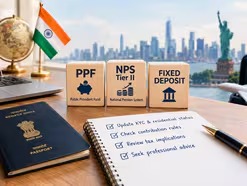
is that NPS Tier II accounts specifically can't be held by non-resident
Indians. The Pension Fund Regulatory and Development Authority doesn't allow outright
closures. That leaves exactly two options: withdraw the entire balance, or
shift it into a Tier I account, which comes with lock-in restrictions. Either
way, one needs to notify the NPS Trust directly so tax is deducted correctly
whenever the money eventually comes out.
PPF works
differently, and more leniently. It can be kept functional until it hits its
15-year maturity without the need to close it early. Extension beyond that
point and opening a new PPF account once classified as an NRI is not a
possibility.
Your Bank
Accounts Need Updating Too
This is the
part people tend to overlook: local KYC records. Changes in residential status when
not communicated to the bank leads to
non-compliance and that can mean frozen assets down the line, not just a
paperwork headache.
For fixed
deposits, the fix is straightforward. Once notified, the bank redesignates the
account as an NRO (Non-Resident Ordinary) deposit, and from there withholding
tax gets deducted on the interest automatically. Financial advisors guard
against early withdrawal of fixed deposits to avoid filing Indian tax returns. This
is usually not worth the trade-off.
Cross-Border
Taxation Compliances
For anyone
settling in the United States, there's a second layer to deal with. The IRS
treats income from Indian retirement accounts such as PPF, NPS, as taxable
foreign income, which means it has to be reported every year. That typically
means filing Form 8938 and the Report of Foreign Bank and Financial Accounts
(FBAR), on top of applicable Indian filings.
To optimize
domestic liabilities, emigrants frequently gift withdrawn capital to resident
parents. Genuine inter-generational transfers avoid local tax clubbing
provisions. This legally reduces the expatriate's Indian income tax footprint.
Why It
Matters
Failure in
KYC updates is a violation of foreign exchange law. Mismanaging PPF or NPS Tier
II holdings can expose expatriates to penalties in two tax jurisdictions
simultaneously, while proper redesignation of accounts protects domestic tax
exemptions. Meanwhile, documented gifting to family members remains one of the
few legal tools available to reduce redundant filing obligations back in India.
Key Facts
at a Glance
- Pension accounts: NPS Tier II balances must be
closed or shifted into Tier I
- Provident funds: Existing PPF accounts stay
valid until 15-year maturity; no extensions, no new accounts for NRIs
- Banking: Fixed deposits must be
converted to NRO status, with withholding tax applied
- US compliance: Indian retirement income must
be reported annually via FBAR and IRS Form 8938
- Tax planning: Documented gifts to resident
parents carry no domestic tax liability
FAQ
Q: Can I
keep my fixed deposits after moving abroad?
A: Yes, just notify your bank of your new residential status. They'll
redesignate it as an NRO deposit and deduct withholding tax on the interest
going forward.
Q: Will I
owe tax on money gifted to my parents?
A: No. Genuine, documented transfers between children and parents don't trigger
tax liability or clubbing provisions under current Indian law.
Q: Are my
Indian retirement accounts taxable once I move to the US?
A: Yes. Once you establish US tax residency, earnings from PPF and NPS accounts
become taxable there and must be reported annually to the IRS.
SOURCE: WOWNEWS24X7, Navraj Global Advisors / FEMA / NPS Trust