India’s data centre sector has achieved 1.57 GW in operational capacity, with projections reaching 8 GW by 2030, driven by 70 billion dollars in investments. Supported by formal infrastructure status, rising AI compute demands, and data sovereignty policies, server hubs are establishing themselves as essential national economic infrastructure.
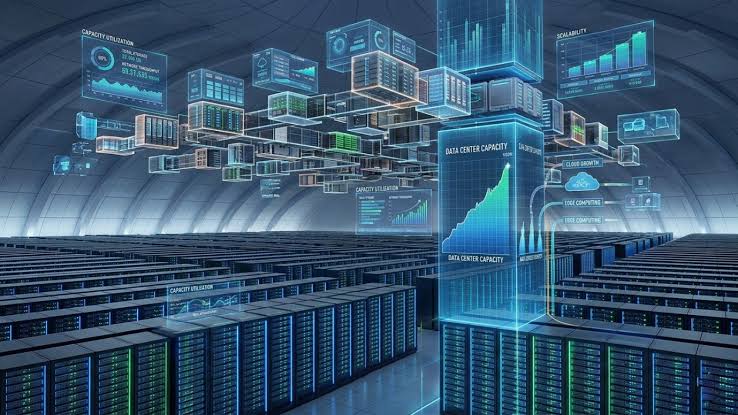
NEW DELHI — Rapid digital transformation across financial technology, public e-governance, and artificial intelligence has firmly established data centres in India as the foundational infrastructure for the modern economy. In a comprehensive review released in September 2026, government authorities highlighted that operational power capacity for domestic server parks has expanded to 1.57 gigawatts (GW), with domestic and overseas project pipelines projected to scale the industry toward nearly 8 GW by 2030. The ongoing acceleration reflects rising domestic data consumption, strict data sovereignty requirements, and massive capital inflows estimated to approach 70 billion USD over the decade.
Policy Catalysts and Infrastructure Status
The institutional expansion of data centres in India stems directly from regulatory decisions granting the sector formal "infrastructure status." This classification enables facility operators and institutional real estate developers to access long-term debt financing at competitive interest rates, streamline land procurement procedures, and benefit from unified state-level single-window approvals.
Multiple coastal and metropolitan hubs—primarily the Mumbai-Navi Mumbai belt, Chennai, Noida, and Bengaluru—now host hyperscale campuses. Coastal landing stations provide low-latency connectivity to transatlantic and Indo-Pacific subsea fiber-optic cables, while inland logistics corridors accommodate enterprise server centers for state agencies and commercial banking systems.
State governments have supplemented central policy by drafting tailored fiscal incentives. Regional policies across Maharashtra, Tamil Nadu, Telangana, and Uttar Pradesh provide targeted stamp duty exemptions, electricity tax concessions, and dedicated green energy corridors to accommodate high-density compute facilities.
Drivers: AI Workloads, 5G Deployments, and Data Sovereignty
The operational demand fueling data centres in India is shifting from simple enterprise storage toward complex, compute-heavy environments. The rollout of nationwide 5G networks, combined with broad enterprise adoption of generative artificial intelligence and large language models (LLMs), has significantly increased rack power densities.
Simultaneously, compliance requirements under the Digital Personal Data Protection (DPDP) framework mandate that critical personal and financial information must reside within sovereign territorial boundaries. As domestic consumer payment networks—including the Unified Payments Interface (UPI)—log billions of monthly transactions, state bodies and financial intermediaries require low-latency domestic storage nodes to ensure business continuity and cybersecurity integrity.
Hyperscale cloud providers, enterprise tech firms, and domestic conglomerates are adjusting development plans to match these compute requirements, shifting from traditional retail colocation to multi-megawatt campuses equipped for liquid cooling and specialized GPU clustering.
Clean Energy Transitions and Power Grid Management
The steep expansion of data centres in India presents significant operational challenges for regional electricity grids. High-density data clusters require uninterruptible power, prompting real estate developers to secure dedicated green energy open-access agreements.
To mitigate reliance on diesel generator backups and fossil-fuel baseload power, operators are directly contracting renewable energy through round-the-clock (RTC) solar, wind, and battery storage power-purchase agreements. State power regulators are also coordinating with operators to locate newer campuses near dedicated green power corridors to balance urban distribution grids.
Market Impact Across Industry, Real Estate, and Employment
The transition toward mega-scale facilities is reshaping multiple commercial sectors:
Commercial Real Estate: Institutional developers and sovereign wealth funds are reallocating commercial portfolios toward institutional digital assets, partnering with global operators to construct multi-acre campuses.
Domestic Enterprise and Startups: Local businesses gain reduced latency and cheaper cloud computing services, improving delivery of digital healthcare, fintech applications, and edtech platforms.
Workforce Development: Constructing and maintaining high-tier server campuses generates demand for specialized power systems engineers, cooling design specialists, cybersecurity analysts, and network technicians.
Official Sources Section
According to official briefings released by the Press Information Bureau and policy updates from the Ministry of Electronics and Information Technology, India's digital economy strategies are anchored in resilient, domestic computing facilities. Supplementary capacity tracking published by the Central Electricity Authority outlines grid connection protocols and energy compliance roadmaps for upcoming hyperscale nodes.
Quote Section
According to official government releases, "Data centres are the invisible engines powering India's digital life, providing the critical foundation that supports banking, e-governance, and citizen-facing online services around the clock".
Industry infrastructure executives noted that "the convergence of artificial intelligence workloads and statutory data governance requirements has transformed digital real estate from an auxiliary service into a top-tier national asset class."
Why It Matters
Data centers have become as essential to modern commerce as physical transport networks and electrical power plants. Securing sovereign compute capacity ensures that citizen privacy remains safeguarded under Indian law, prevents international network disruptions from paralyzing public services, and positions the domestic economy as a major compute hub for South Asia.
Key Facts at a Glance
Power Capacity Trajectory: Operational capacity stands at 1.57 GW as of August 2026, with forecasts pointing toward nearly 8 GW by 2030.
Investment Volume: Projected capital deployment into domestic server campuses is expected to approach 70 billion USD by 2030.
Policy Backing: Central infrastructure status provides cheaper capital access and simplified administrative approvals.
Geographic Nodes: Leading clusters remain concentrated in Mumbai, Chennai, Noida, Bengaluru, and Hyderabad.
Frequently Asked Questions
Why are data centres considered critical infrastructure in India?
They provide the processing power and storage necessary to operate public e-governance portals, digital banking networks, emergency services, and commercial internet applications.
What is driving the surge in data centre capacity across India?
The rapid expansion is propelled by enterprise AI integration, widespread 5G data traffic, digital public infrastructure adoption, and regulatory compliance under the Digital Personal Data Protection Act.
How are power and cooling challenges being addressed?
Operators are adopting round-the-clock renewable energy open-access deals, battery energy storage systems, and advanced liquid cooling technologies to lower carbon footprints and optimize power usage effectiveness.
Source: Press Information Bureau (PIB); Ministry of Electronics and Information Technology (MeitY); Central Electricity Authority (CEA)