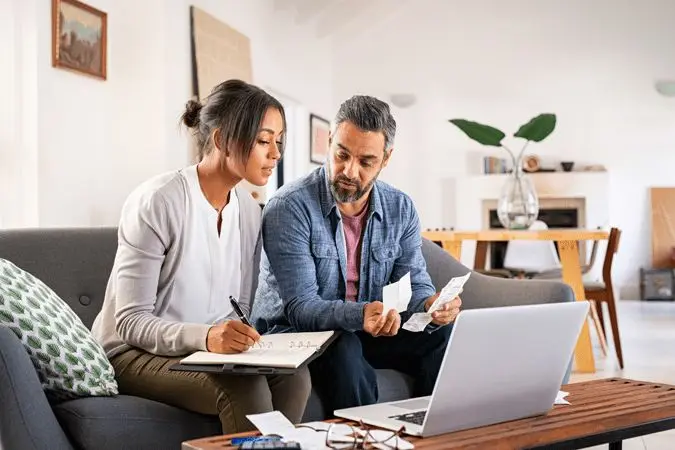
Modern families increasingly prioritize financial independence discussions to align household budgets, individual savings, and long-term security goals. Economic shifts and changing marital dynamics drive couples to establish transparent communication channels regarding personal debt, investment portfolios, and joint expenses, ensuring mutual financial resilience and preventing unexpected monetary conflicts over time.
Economic volatility and shifting household dynamics drive couples to prioritize open financial independence talks before merging long-term assets.
Household financial planning underwent a quiet structural shift in September 2026, as married couples and domestic partners increasingly formalized discussions surrounding personal financial independence. According to family economics surveys and financial advisory disclosures released this month, younger households are moving away from traditional, fully pooled monetary structures. Instead, couples establish structured dialogues regarding individual savings accounts, debt liabilities, and proportional expense sharing to mitigate long-term economic friction.
Evaluating Shared Budgets, Household Debt, and Financial Transparency
Analyzing the shift toward independent monetary management reveals changing attitudes regarding personal autonomy within modern partnerships. According to official consumer finance disclosures and behavioral economic studies published in September 2026, key factors include:
Proportional Expense Allocation: Households increasingly adopt tiered budgeting models where partners contribute to joint living costs based on individual income ratios rather than 50-50 splits.
Debt Liability Disclosures: Couples prioritize transparent pre-marital and early-marriage disclosures regarding student loans, credit card balances, and personal credit scores.
Autonomous Savings Pools: Financial advisors recommend maintaining separate discretionary accounts to preserve personal spending freedom while funding joint emergency funds.
Risk Mitigation Strategies: Clear boundaries around individual investments protect both partners from unexpected economic shocks, business failures, or unsecured liabilities.
Why It Matters
The practical implications of conducting early financial independence discussions impact divorce rates, household credit health, and long-term retirement security. For families and couples, open communication prevents hidden debt accumulation and reduces marital stress caused by misaligned spending habits. For financial institutions, catering to dual-income households with hybrid account structures remains a growing commercial priority.
Key Facts at a Glance
Core Trend: Increasing frequency of financial independence talks among modern couples.
Primary Objective: Balancing individual monetary autonomy with shared household expense management.
Recommended Practice: Establishing proportional contribution models and transparent debt disclosures.
Governing Research: Monitored via the Consumer Financial Protection Bureau (CFPB).
FAQ Section
Why are couples discussing financial independence more frequently today?
Shifting economic pressures and delayed marriage timelines encourage partners to prioritize open monetary communication and protect personal credit profiles.
How do modern households manage shared expenses without pooling all funds?
Many couples utilize hybrid budgeting systems, maintaining separate personal accounts while funding a joint account proportionally for mutual living costs.
What risks do couples face by avoiding financial discussions?
Unspoken debts, mismatched spending habits, and divergent retirement goals can trigger severe household friction and financial instability.
Where can families find professional guidance on joint financial planning?
Advisory frameworks and consumer toolkits are regularly published by organizations like the CFPB and certified financial planning boards.
Source: Consumer Financial Protection Bureau (CFPB), Federal Reserve, Certified Financial Planner Board, Reuters Financial Desk